Subject-to deals became one of the most talked-about strategies of 2025–26. Millions of homeowners hold mortgages at 2.75–4% from before 2022, and an investor who can take over that payment gets financing no bank would offer today. This guide explains how a subject-to deal works, the numbers that decide it, and the risks.
01What does "subject-to" mean?
In a subject-to purchase the seller deeds the property to you, but their existing mortgage stays in place and in their name. You buy "subject to" that loan and make the payments. No new loan, no bank approval, and often a very low interest rate.
02Who sells subject-to, and why?
- Owners behind on payments who need to stop a foreclosure.
- Owners with little equity who cannot pay commissions and closing costs to list.
- Tired landlords, relocations and inherited houses where speed matters more than price.
03The numbers: entry fee
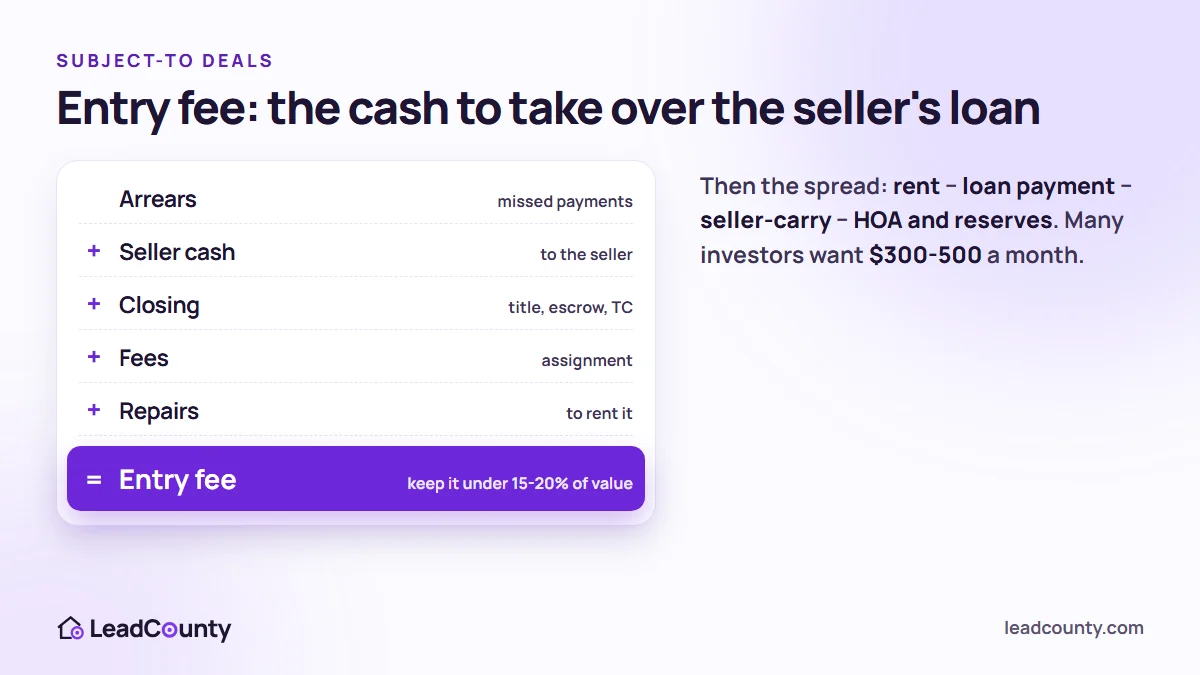
The entry fee is the cash to get into the deal: missed payments (arrears) + cash to the seller + closing and transaction costs + any wholesale or acquisition fee + repairs to rent it out. Many creative buyers want the entry fee at 15–20% of the property's value or less.
04The numbers: monthly spread
Spread = market rent − the loan payment (principal and interest plus the taxes and insurance escrow) − any seller-carry payment − HOA and reserves for vacancy, repairs and management. A healthy single-family subject-to deal often shows $300–500 a month.
05Equity, total debt and the purchase price
Total debt = the existing loan balance plus any second loan or seller-carry note. Equity = ARV − total debt. Investors often describe the "purchase price" as the debt plus the entry fee. Deals posted in investor groups in 2026 typically list: loan balance and rate, PITI, seller-carry amount, rate and balloon, taxes, HOA, total monthly payment, total debt, ARV, equity spread and entry fee. The subject-to calculator shows exactly these lines.
06Adding a seller-carry second
When the seller has more equity than you can pay in cash, the seller can carry a second note: you pay them monthly at an agreed rate, often with a balloon after 3–10 years. The calculator shows the blended interest rate across both loans and the balance due when the balloon comes.
07Subject-to vs seller financing
- Subject-to: the seller's bank loan stays; you pay it. Best when the seller has a low-rate loan and little equity.
- Seller financing: the seller lends to you directly, usually on a free-and-clear house. Best for long-time owners who want monthly income.
- Many deals combine both: subject-to the first loan, seller-carry for part of the equity.
08The due-on-sale clause and other risks
Most mortgages let the lender call the loan due when the title changes. Lenders rarely do it while payments are current, but you must plan for it: have a refinance or sale plan, keep reserves, and never let payments lapse. Protect both sides with escrow, a recorded deed, title insurance, written disclosures and a real-estate attorney. Some states have specific rules for these deals, so check yours.
09Where subject-to leads come from
Pre-foreclosure filings, owners behind on taxes, inherited houses and long-time landlords are the usual starting points. LeadCounty finds them in county court, treasurer and recorder records every week.
Run any deal through the free subject-to calculator first: it shows the entry fee, the spread, the equity and the cash-on-cash return with every step of the math.