DSCR loans let real estate investors qualify on the property's rent instead of their personal income. They power most BRRRR refinances and many rental purchases in 2026. Here is how lenders calculate the ratio, what they want to see, and the mistake many investors make with it.
01What is a DSCR loan?
A debt service coverage ratio (DSCR) loan is an investment-property mortgage where the lender checks whether the rent covers the payment, not your tax returns. It suits self-employed investors, people with several rentals, and BRRRR investors refinancing out of a short-term loan.
02How do lenders calculate DSCR?
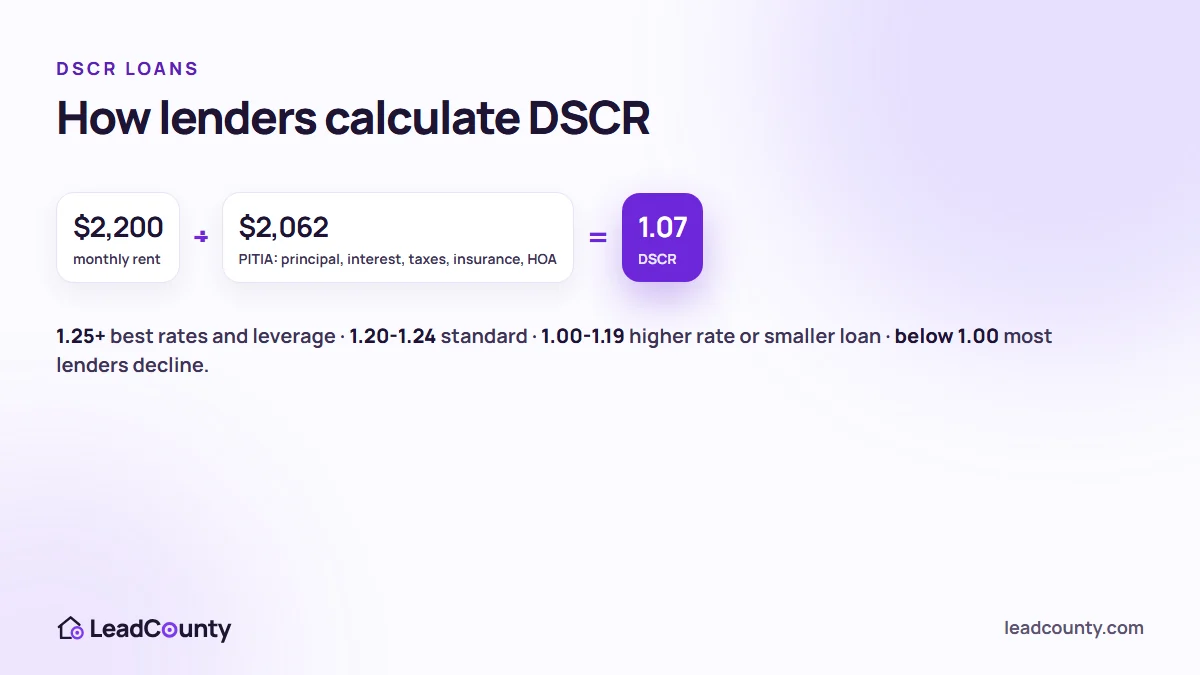
Most DSCR lenders use: DSCR = monthly rent ÷ PITIA. PITIA is principal and interest plus property taxes, insurance and any HOA. Example: rent $2,200; a $240,000 loan at 7.25% over 30 years costs about $1,637 a month; taxes $300, insurance $125. PITIA = $2,062, so DSCR = 1.07.
03What DSCR do you need in 2026?
- 1.25 or more: the best rates and the highest leverage.
- 1.20–1.24: standard pricing with most lenders.
- 1.00–1.19: possible with some lenders, usually with a higher rate or a lower loan amount.
- Below 1.00: the rent does not cover the payment; most programs say no.
04How much can you borrow?
Typical 2026 limits are 75–80% of the value on a purchase and 70–75% on a cash-out refinance (short-term rentals often 70%). The rent sets a second limit: at a 1.25 minimum, the largest payment the lender allows is rent ÷ 1.25 minus taxes, insurance and HOA. The DSCR calculator turns that into the largest loan.
05Interest-only DSCR loans
Many lenders offer an interest-only period. The payment is lower, so the DSCR is higher, but you pay down no principal during that time.
06DSCR is not cash flow
This is the most common mistake. Lender DSCR ignores vacancy, repairs, capital items and management. A rental at DSCR 1.10 can easily lose money once you set aside 20% of the rent for those costs. Always check real cash flow too; the DSCR calculator shows both lines.
07DSCR and the BRRRR refinance
In a BRRRR deal the refinance is a DSCR loan. If the appraisal comes in low or the rent is weak, the new loan is smaller and more of your cash stays in the deal. Run the BRRRR calculator before you buy, using a conservative ARV and real rent.
08Other things lenders check
- Seasoning: often about 6 months of ownership before a cash-out refinance; some allow 90 days.
- Credit score and reserves (often six months of PITIA).
- A rent schedule from the appraiser, or a lease.
Check any rental with the free DSCR calculator: the lender's ratio, the real cash flow and the largest loan the rent supports, with every step shown.